All Categories
Featured
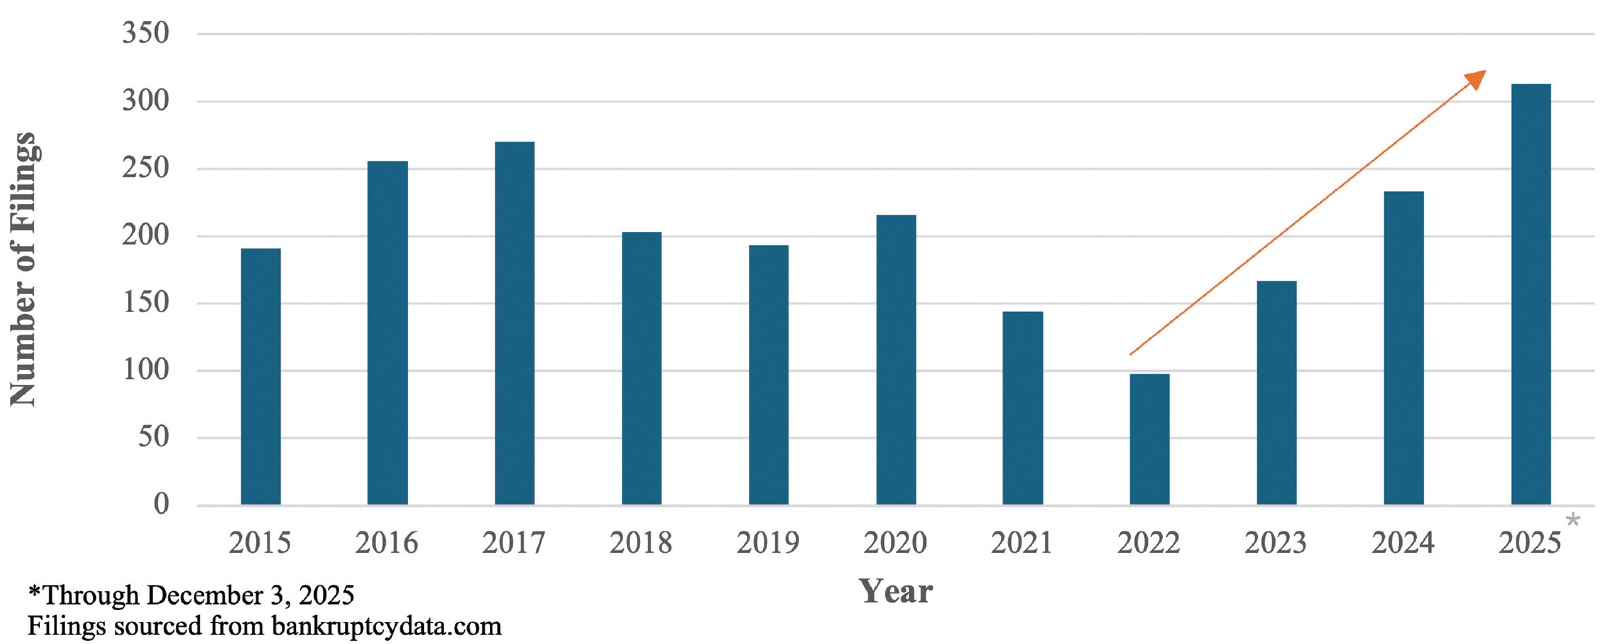
When to Select Insolvency in 2026
That's you. If you are overwhelmed with debt, make sure you consider all debt relief options and determine what's finest for you.
As we enter 2026, the insolvency landscape is expected to shift in manner ins which will significantly affect creditors this year. After years of post-pandemic unpredictability, filings are climbing up gradually, and financial pressures continue to impact customer behavior. Throughout a recent Ask a Pro webinar, our specialists, Shareholder Milos Gvozdenovic and Lawyer Garry Masterson, weighed in on what lending institutions should anticipate in the coming year.
For a much deeper dive into all the commentary and concerns addressed, we advise watching the complete webinar. The most prominent trend for 2026 is a sustained increase in personal bankruptcy filings. While filings have actually not reached pre-COVID levels, month-over-month growth recommends we're on track to surpass them soon. As of September 30, 2025, bankruptcy filings increased by 10.6 percent compared to the previous fiscal year.
How to File for Bankruptcy in 2026
While chapter 13 filings continue to heighten, chapter 7 filings, the most typical type of consumer insolvency, are anticipated to control court dockets. This trend is driven by consumers' absence of disposable income and installing financial pressure.
You need to likewise prepare for increased delinquency rates on automobile loans and home mortgages. It's likewise crucial to carefully monitor credit portfolios as financial obligation levels remain high.
We predict that the genuine impact will hit in 2027, when these foreclosures move to conclusion and trigger personal bankruptcy filings. How can financial institutions stay one action ahead of mortgage-related insolvency filings?
Serious Legal Impacts of 2026 BankruptcyMany approaching defaults might develop from formerly strong credit sections. Over the last few years, credit reporting in insolvency cases has become one of the most contentious topics. This year will be no various. However it is necessary that lenders stand company. If a debtor does not declare a loan, you need to not continue reporting the account as active.
Here are a couple of more best practices to follow: Stop reporting released debts as active accounts. Resume normal reporting just after a reaffirmation contract is signed and submitted.
Why to Consider Bankruptcy in 2026
Another trend to watch is the increase in pro se filingscases filed without lawyer representation. These cases frequently develop procedural problems for financial institutions. Some debtors might fail to precisely divulge their possessions, income and expenditures. They can even miss out on crucial court hearings. Again, these problems add complexity to personal bankruptcy cases.
Some current college graduates may juggle responsibilities and resort to insolvency to handle overall debt. The failure to best a lien within 30 days of loan origination can result in a financial institution being dealt with as unsecured in bankruptcy.
Think about protective measures such as UCC filings when delays happen. The bankruptcy landscape in 2026 will continue to be shaped by financial unpredictability, regulative examination and developing consumer habits.
By preparing for the patterns mentioned above, you can reduce exposure and preserve functional resilience in the year ahead. If you have any questions or concerns about these forecasts or other personal bankruptcy subjects, please link with our Insolvency Recovery Group or contact Milos or Garry straight any time. This blog is not a solicitation for organization, and it is not planned to make up legal recommendations on specific matters, create an attorney-client relationship or be legally binding in any way.

Latest Posts
Essential Bankruptcy Support Resources for 2026 Filers
Chapter 7 and Chapter 13
Total Lawyer Fees for 2026